
Captive Insurance Services
Structures we work with
Single parent captives. A captive insuring the risks of its owner and affiliates. The most common structure and the one where tax documentation matters most.
Group captives. Multiple unrelated owners sharing a captive, whether homogeneous by industry or heterogeneous.
Protected and segregated cells. Cell facilities and the individual cells within them, including the presentation questions that arise when cells are audited separately from the core.
Risk retention groups. Operating across states under the federal Liability Risk Retention Act, with the multi state filing profile that creates.
Special purpose captives. Captives established for a specific transaction, financing arrangement, or defined insurance program, often with a limited purpose and structure tailored to the particular risks being assumed.

WHAT IS A CAPTIVE INSURANCE COMPANY?
A captive insurance company is a privately owned insurance entity formed by a business or group of businesses to insure their own risks. Instead of purchasing coverage from a traditional insurance carrier, the parent company uses the captive to provide customized insurance solutions, manage risk more effectively, and gain greater control over premiums and claims.

WHAT IS THE PRIMARY USE FOR FORMING A CAPTIVE INSURANCE COMPANY?
The primary purpose of forming a captive insurance company is to improve risk management while potentially reducing insurance costs. Captives allow organizations to tailor coverage to their specific risks, stabilize insurance expenses, access reinsurance markets, and, in some cases, achieve tax efficiencies when structured and managed properly under applicable regulations.

WHAT DOES A CAPTIVE INSURANCE AUDITOR DO?
A captive insurance auditor provides an independent examination of a captive insurance company’s financial statements to ensure compliance with accounting standards. Captive audits focus heavily on premium recognition, loss reserves, related-party transactions, and coordination with actuarial reports.

HOW IS A CAPTIVE INSURANCE AUDIT DIFFERENT FROM A TRADITIONAL INSURANCE AUDIT?
Captive insurance audits require specialized knowledge of risk transfer, risk distribution, intercompany arrangements, and regulatory expectations unique to captive domiciles. Unlike traditional insurance audits, captives involve closely held entities, related parties, and heightened regulatory and IRS scrutiny.

WHY IS IRS SCRUTINY A CONCERN FOR CAPTIVE INSURANCE COMPANIES?
The IRS closely examines captive insurance arrangements—particularly small captives under IRC §831(b)—to ensure they operate as real insurance companies. Key IRS focus areas include risk transfer, risk distribution, premium pricing, claims history, and proper documentation.

WHAT TYPES OF CAPTIVE INSURANCE COMPANIES DOES LARSON WORK WITH?
Our captive specialists typically work with single-parent captives, group captives, and risk retention structures across a range of industries. Some of these industries often include captives insuring operating companies, professional services firms, manufacturers, and middle-market businesses.

HOW DO YOU COORDINATE WITH CAPTIVE MANAGERS AND ACTUARIES?
Our captive specialists collaborate closely with captive managers and actuaries to align financial statements, actuarial reports, and regulatory filings. This coordination helps ensure consistency across audit, tax, and regulatory submissions.

HOW ARE PREMIUMS AND LOSS RESERVES HANDLED FOR CAPTIVE TAX PURPOSES?
Premiums must be actuarially supported, reasonable, and tied to real business risk. Loss reserves must be calculated consistently with actuarial reports and accounting standards. Conservative treatment and clear documentation reduce IRS risk.

WHAT ARE COMMON MISTAKES THAT CAUSE PROBLEMS FOR CAPTIVE INSURANCE COMPANIES?
Common issues include poorly documented risk transfer, unsupported premiums, limited claims activity, inadequate governance, and lack of coordination between auditors, actuaries, and captive managers.

WHAT INFORMATION DO YOU NEED TO GET STARTED WITH A CAPTIVE AUDIT OR TAX ENGAGEMENT?
Typical requirements include financial records, actuarial reports, captive agreements, claims data, prior filings, and operating company information. A structured onboarding process helps keep timelines predictable.

HOW FAR IN ADVANCE SHOULD A CAPTIVE INSURANCE COMPANY PLAN FOR AUDIT AND TAX FILINGS?
Planning should begin several months before filing deadlines. Early coordination allows time to resolve issues, align documentation, and avoid last-minute regulatory or tax complications.

WHEN SHOULD A CAPTIVE INSURANCE COMPANY RECONSIDER ITS STRUCTURE OR EXIT STRATEGY?
Captive owners should periodically review whether the captive still meets business, regulatory, and tax objectives. Changes in risk profile, regulations, or IRS guidance may signal the need for restructuring or an orderly unwind.

DO YOU WORK WITH SPECIFIC CAPTIVE DOMICILES?
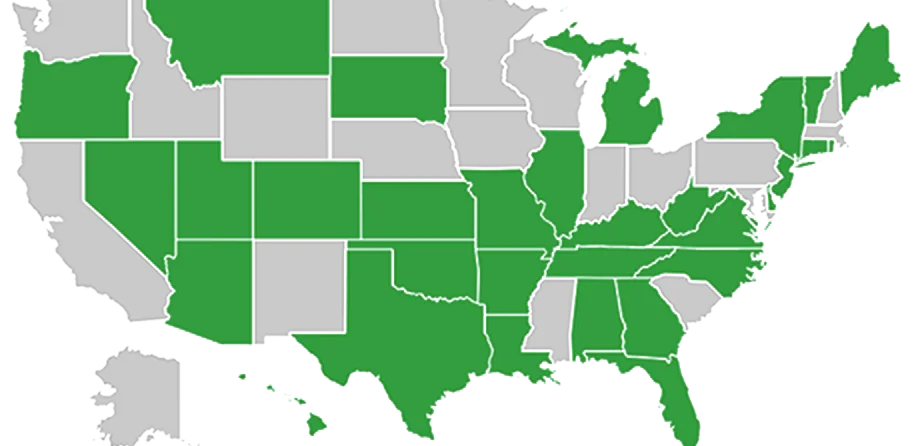
We are licensed to perform captive audit work in all US states with captive law, including Arizona, Vermont, Utah, Delaware, Texas, and many others. Familiarity with domicile-specific regulatory requirements is essential for timely and accepted filings. We have great relationships with state captive insurance regulators, which in turn helps us understand your reporting needs and your domicile's unique requirements.







